By using this site, you agree to the Privacy Policy and Terms of Use.
Accept
Reaper Scans
  • Business
  • Lifestyle
  • Health
  • Travel
  • Crypto
  • Finance
  • Blog
    • Tech
    • Contact Us
Reaper ScansReaper Scans
Search
Follow US
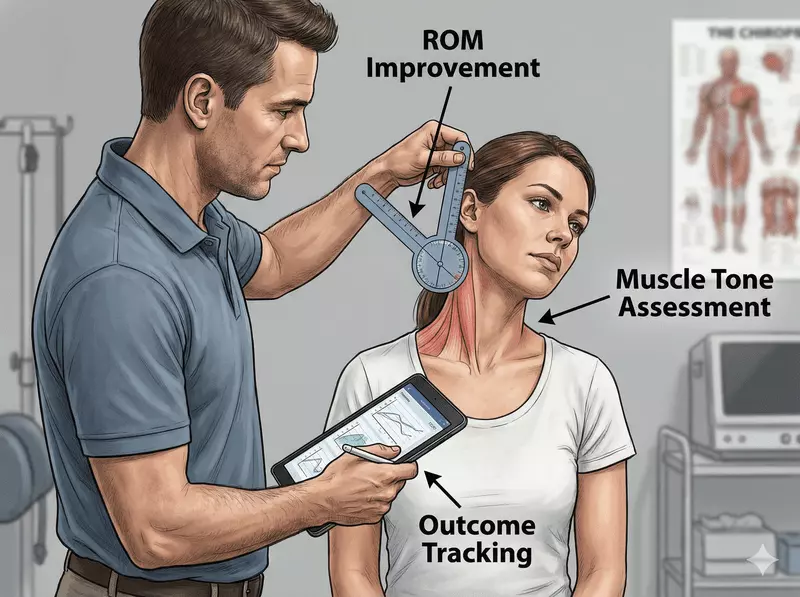
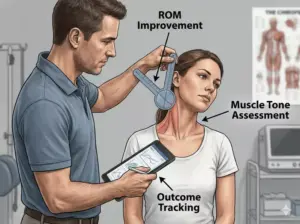
Alternative Therapies for Neck Pain Treatment
Health

Alternative Therapies for Neck Pain Treatment

By Robert
4 hours ago
How Does a Cosmetic Dentist Place Crowns and Veneers?
Health

How Does a Cosmetic Dentist Place Crowns and Veneers?

How Global Businesses Can Build A Smarter Cross-Border Treasury Plan ________________________________________ Key Takeaways • A defined treasury plan helps reduce payment delays, avoidable conversion costs, and cash flow surprises. • Each payment corridor should be assessed for cost, speed, reliability, settlement timing, and compliance needs. • Currency balances, approval rules, and cash forecasts deserve the same attention as payment tools. • New settlement technology can be useful, but only with sound accounting, controls, and backup routes. International growth can create a cash management problem long before it creates a revenue problem. A company may collect payments in one currency, pay teams in several others, and still need dependable access to cash for taxes, suppliers, and payroll. An offshore business account may be part of that structure when it supports legitimate operational needs. Still, it should fit into a broader plan for visibility, approvals, recordkeeping, and currency management. A smarter treasury plan is not necessarily complicated. It is a practical system for knowing where money is held, what payments are due, how funds move between countries, and who can authorize each transaction. The goal is to make daily decisions more predictable while preserving flexibility when a supplier, customer, or market condition changes. Why Treasury Planning Matters For Global Businesses Cross-border payments involve more moving parts than domestic transfers. Currencies, banking hours, local payment systems, intermediary institutions, and legal frameworks can all affect the outcome. The complexity of payments across multiple jurisdictions helps explain why a transfer that seems routine can take longer or cost more than expected. Consider a software company that receives subscription revenue in euros, pays contractors in U.S. dollars, and settles local vendor invoices in other currencies. It can be profitable on paper while still facing a short-term cash constraint if customer receipts arrive late, conversion is delayed, or too much money is held in a currency that cannot cover the next obligation. Map Every Money Flow Start with a simple inventory of where money enters and leaves the business. Do not limit the review to major supplier payments. Small, recurring transactions and exception payments often reveal operational gaps. Include These Categories • Customer receipts, refunds, and chargebacks. • Supplier invoices, payroll, and contractor payments. • Taxes, government fees, and insurance obligations. • Transfers between company accounts and reserve balances. For each recurring flow, record the country, currency, usual amount, timing, recipient, payment method, and approver. Then ask where delays occur, which currencies create the greatest conversion expense, and how much cash must remain available over the next 30, 60, and 90 days. Choose The Right Payment Rails No single payment method works best for every corridor. Traditional bank transfers are well-suited to established supplier relationships and higher-value payments. Local payment networks may be practical for recurring in-country expenses. Card networks can support customer purchases and lower operating costs, while faster payment systems may improve access to funds where they are supported. Compare routes based on the total cost, quoted exchange rate, settlement time, delivery certainty, tracking, transaction limits, and refund process. A low upfront fee is not automatically the lowest-cost option if the exchange spread, manual work, or delayed settlement creates additional expense. Manage Currency Risk With Simple Rules Currency management should support operations rather than become speculation. Set target balances for the currencies used most often, keep enough local funds for near-term commitments, and convert excess balances according to a documented schedule. Forecast known needs before large invoices, payroll cycles, or tax deadlines. A practical policy might require the company to maintain a defined operating balance in each core currency, review material exposures monthly, and require additional approval for conversions above a chosen threshold. Track the full conversion cost, including fees and spreads, so decisions are based on actual results. Build Compliance Controls Into The Process Faster payments do not remove the need for verification. Confirm the legal name and account details for each recipient, retain invoices and contracts with payment records, and set approval limits that reflect the payment value and risk. Unusual, high-value, or first-time transfers should receive closer review. Requirements can differ by jurisdiction, industry, and transaction type. Businesses should review relevant sanctions, reporting, tax, and recordkeeping duties, then seek qualified legal or tax advice when a requirement is unclear. Improve Cash Visibility A basic dashboard can turn fragmented account data into useful decisions. Track available cash by currency, expected receipts, upcoming payments by country, reserve balances, delayed transfers, failed payments, average settlement time, and average conversion cost. Businesses with frequent international activity should review this information weekly. Companies with fewer transactions may use a monthly review, provided they also monitor upcoming deadlines and major currency exposures between reviews. Use New Payment Tools With Care Technology can improve automation, reconciliation, and speed, but it does not replace operational discipline. Test a new provider or settlement route in one corridor first. Confirm how funds are safeguarded, converted, withdrawn, recorded in accounting systems, and supported if a payment fails. Research into tokenized wholesale settlement is also progressing. The work toward real-value testing in Project Agorá illustrates how tokenized central bank reserves and commercial bank deposits are being explored for wholesale cross-border payments. For most businesses, however, current tools should be judged on proven controls, practical availability, and fit with existing workflows. A Practical Treasury Checklist 1. List every country and currency involved in sending or receiving funds. 2. Measure current fees, conversion spreads, and settlement times. 3. Set minimum cash reserves for essential obligations. 4. Create clear approval levels and maintain payment documentation. 5. Choose a primary and backup route for important payment corridors. 6. Connect payment records to accounting and reporting processes. 7. Test changes with smaller transactions before scaling them. 8. Review the full treasury process at least quarterly. Common Questions What Is A Cross-Border Treasury Plan? It is a written process for managing international cash, currencies, payment methods, reserves, approvals, and financial risk. Should A Small Business Have One? Yes. It can be as simple as a payment calendar, a cash spreadsheet, target currency balances, and clear approval rules. Are Faster Payments Always Better? No. Speed matters, but so do total cost, tracking, compliance checks, accuracy, and the ability to resolve exceptions. Conclusion A strong cross-border treasury plan combines clear records, sensible currency rules, reliable payment routes, and routine compliance checks. Businesses should test their processes, measure the actual cost of each corridor, maintain a backup option for urgent payments, and choose tools that improve both control and speed.
Finance

How Global Businesses Can Build A Smarter Cross-Border Treasury Plan

FAQs About Allergy Treatments
Health

FAQs About Allergy Treatments

Blog

The Future of Allergy Testing

By Robert
1 day ago
Blog

Using Therapy To Navigate the Challenges of Adult ADHD

By Robert
4 days ago
Health

How to Make Preventive Dental Care Fit Your Budget

By Robert
5 days ago
How Does a Cosmetic Dentist Place Crowns and Veneers?
Health

How Does a Cosmetic Dentist Place Crowns and Veneers?

How Global Businesses Can Build A Smarter Cross-Border Treasury Plan ________________________________________ Key Takeaways • A defined treasury plan helps reduce payment delays, avoidable conversion costs, and cash flow surprises. • Each payment corridor should be assessed for cost, speed, reliability, settlement timing, and compliance needs. • Currency balances, approval rules, and cash forecasts deserve the same attention as payment tools. • New settlement technology can be useful, but only with sound accounting, controls, and backup routes. International growth can create a cash management problem long before it creates a revenue problem. A company may collect payments in one currency, pay teams in several others, and still need dependable access to cash for taxes, suppliers, and payroll. An offshore business account may be part of that structure when it supports legitimate operational needs. Still, it should fit into a broader plan for visibility, approvals, recordkeeping, and currency management. A smarter treasury plan is not necessarily complicated. It is a practical system for knowing where money is held, what payments are due, how funds move between countries, and who can authorize each transaction. The goal is to make daily decisions more predictable while preserving flexibility when a supplier, customer, or market condition changes. Why Treasury Planning Matters For Global Businesses Cross-border payments involve more moving parts than domestic transfers. Currencies, banking hours, local payment systems, intermediary institutions, and legal frameworks can all affect the outcome. The complexity of payments across multiple jurisdictions helps explain why a transfer that seems routine can take longer or cost more than expected. Consider a software company that receives subscription revenue in euros, pays contractors in U.S. dollars, and settles local vendor invoices in other currencies. It can be profitable on paper while still facing a short-term cash constraint if customer receipts arrive late, conversion is delayed, or too much money is held in a currency that cannot cover the next obligation. Map Every Money Flow Start with a simple inventory of where money enters and leaves the business. Do not limit the review to major supplier payments. Small, recurring transactions and exception payments often reveal operational gaps. Include These Categories • Customer receipts, refunds, and chargebacks. • Supplier invoices, payroll, and contractor payments. • Taxes, government fees, and insurance obligations. • Transfers between company accounts and reserve balances. For each recurring flow, record the country, currency, usual amount, timing, recipient, payment method, and approver. Then ask where delays occur, which currencies create the greatest conversion expense, and how much cash must remain available over the next 30, 60, and 90 days. Choose The Right Payment Rails No single payment method works best for every corridor. Traditional bank transfers are well-suited to established supplier relationships and higher-value payments. Local payment networks may be practical for recurring in-country expenses. Card networks can support customer purchases and lower operating costs, while faster payment systems may improve access to funds where they are supported. Compare routes based on the total cost, quoted exchange rate, settlement time, delivery certainty, tracking, transaction limits, and refund process. A low upfront fee is not automatically the lowest-cost option if the exchange spread, manual work, or delayed settlement creates additional expense. Manage Currency Risk With Simple Rules Currency management should support operations rather than become speculation. Set target balances for the currencies used most often, keep enough local funds for near-term commitments, and convert excess balances according to a documented schedule. Forecast known needs before large invoices, payroll cycles, or tax deadlines. A practical policy might require the company to maintain a defined operating balance in each core currency, review material exposures monthly, and require additional approval for conversions above a chosen threshold. Track the full conversion cost, including fees and spreads, so decisions are based on actual results. Build Compliance Controls Into The Process Faster payments do not remove the need for verification. Confirm the legal name and account details for each recipient, retain invoices and contracts with payment records, and set approval limits that reflect the payment value and risk. Unusual, high-value, or first-time transfers should receive closer review. Requirements can differ by jurisdiction, industry, and transaction type. Businesses should review relevant sanctions, reporting, tax, and recordkeeping duties, then seek qualified legal or tax advice when a requirement is unclear. Improve Cash Visibility A basic dashboard can turn fragmented account data into useful decisions. Track available cash by currency, expected receipts, upcoming payments by country, reserve balances, delayed transfers, failed payments, average settlement time, and average conversion cost. Businesses with frequent international activity should review this information weekly. Companies with fewer transactions may use a monthly review, provided they also monitor upcoming deadlines and major currency exposures between reviews. Use New Payment Tools With Care Technology can improve automation, reconciliation, and speed, but it does not replace operational discipline. Test a new provider or settlement route in one corridor first. Confirm how funds are safeguarded, converted, withdrawn, recorded in accounting systems, and supported if a payment fails. Research into tokenized wholesale settlement is also progressing. The work toward real-value testing in Project Agorá illustrates how tokenized central bank reserves and commercial bank deposits are being explored for wholesale cross-border payments. For most businesses, however, current tools should be judged on proven controls, practical availability, and fit with existing workflows. A Practical Treasury Checklist 1. List every country and currency involved in sending or receiving funds. 2. Measure current fees, conversion spreads, and settlement times. 3. Set minimum cash reserves for essential obligations. 4. Create clear approval levels and maintain payment documentation. 5. Choose a primary and backup route for important payment corridors. 6. Connect payment records to accounting and reporting processes. 7. Test changes with smaller transactions before scaling them. 8. Review the full treasury process at least quarterly. Common Questions What Is A Cross-Border Treasury Plan? It is a written process for managing international cash, currencies, payment methods, reserves, approvals, and financial risk. Should A Small Business Have One? Yes. It can be as simple as a payment calendar, a cash spreadsheet, target currency balances, and clear approval rules. Are Faster Payments Always Better? No. Speed matters, but so do total cost, tracking, compliance checks, accuracy, and the ability to resolve exceptions. Conclusion A strong cross-border treasury plan combines clear records, sensible currency rules, reliable payment routes, and routine compliance checks. Businesses should test their processes, measure the actual cost of each corridor, maintain a backup option for urgent payments, and choose tools that improve both control and speed.
Finance

How Global Businesses Can Build A Smarter Cross-Border Treasury Plan

FAQs About Allergy Treatments
Health

FAQs About Allergy Treatments

The Future of Allergy Testing
Blog

The Future of Allergy Testing

- Sponsored -
reaperscanss

Business

View All
Alternative Therapies for Neck Pain Treatment
Health

Alternative Therapies for Neck Pain Treatment

By Robert
4 hours ago
How Does a Cosmetic Dentist Place Crowns and Veneers?
Health

How Does a Cosmetic Dentist Place Crowns and Veneers?

By Robert
4 hours ago
How Global Businesses Can Build A Smarter Cross-Border Treasury Plan ________________________________________ Key Takeaways • A defined treasury plan helps reduce payment delays, avoidable conversion costs, and cash flow surprises. • Each payment corridor should be assessed for cost, speed, reliability, settlement timing, and compliance needs. • Currency balances, approval rules, and cash forecasts deserve the same attention as payment tools. • New settlement technology can be useful, but only with sound accounting, controls, and backup routes. International growth can create a cash management problem long before it creates a revenue problem. A company may collect payments in one currency, pay teams in several others, and still need dependable access to cash for taxes, suppliers, and payroll. An offshore business account may be part of that structure when it supports legitimate operational needs. Still, it should fit into a broader plan for visibility, approvals, recordkeeping, and currency management. A smarter treasury plan is not necessarily complicated. It is a practical system for knowing where money is held, what payments are due, how funds move between countries, and who can authorize each transaction. The goal is to make daily decisions more predictable while preserving flexibility when a supplier, customer, or market condition changes. Why Treasury Planning Matters For Global Businesses Cross-border payments involve more moving parts than domestic transfers. Currencies, banking hours, local payment systems, intermediary institutions, and legal frameworks can all affect the outcome. The complexity of payments across multiple jurisdictions helps explain why a transfer that seems routine can take longer or cost more than expected. Consider a software company that receives subscription revenue in euros, pays contractors in U.S. dollars, and settles local vendor invoices in other currencies. It can be profitable on paper while still facing a short-term cash constraint if customer receipts arrive late, conversion is delayed, or too much money is held in a currency that cannot cover the next obligation. Map Every Money Flow Start with a simple inventory of where money enters and leaves the business. Do not limit the review to major supplier payments. Small, recurring transactions and exception payments often reveal operational gaps. Include These Categories • Customer receipts, refunds, and chargebacks. • Supplier invoices, payroll, and contractor payments. • Taxes, government fees, and insurance obligations. • Transfers between company accounts and reserve balances. For each recurring flow, record the country, currency, usual amount, timing, recipient, payment method, and approver. Then ask where delays occur, which currencies create the greatest conversion expense, and how much cash must remain available over the next 30, 60, and 90 days. Choose The Right Payment Rails No single payment method works best for every corridor. Traditional bank transfers are well-suited to established supplier relationships and higher-value payments. Local payment networks may be practical for recurring in-country expenses. Card networks can support customer purchases and lower operating costs, while faster payment systems may improve access to funds where they are supported. Compare routes based on the total cost, quoted exchange rate, settlement time, delivery certainty, tracking, transaction limits, and refund process. A low upfront fee is not automatically the lowest-cost option if the exchange spread, manual work, or delayed settlement creates additional expense. Manage Currency Risk With Simple Rules Currency management should support operations rather than become speculation. Set target balances for the currencies used most often, keep enough local funds for near-term commitments, and convert excess balances according to a documented schedule. Forecast known needs before large invoices, payroll cycles, or tax deadlines. A practical policy might require the company to maintain a defined operating balance in each core currency, review material exposures monthly, and require additional approval for conversions above a chosen threshold. Track the full conversion cost, including fees and spreads, so decisions are based on actual results. Build Compliance Controls Into The Process Faster payments do not remove the need for verification. Confirm the legal name and account details for each recipient, retain invoices and contracts with payment records, and set approval limits that reflect the payment value and risk. Unusual, high-value, or first-time transfers should receive closer review. Requirements can differ by jurisdiction, industry, and transaction type. Businesses should review relevant sanctions, reporting, tax, and recordkeeping duties, then seek qualified legal or tax advice when a requirement is unclear. Improve Cash Visibility A basic dashboard can turn fragmented account data into useful decisions. Track available cash by currency, expected receipts, upcoming payments by country, reserve balances, delayed transfers, failed payments, average settlement time, and average conversion cost. Businesses with frequent international activity should review this information weekly. Companies with fewer transactions may use a monthly review, provided they also monitor upcoming deadlines and major currency exposures between reviews. Use New Payment Tools With Care Technology can improve automation, reconciliation, and speed, but it does not replace operational discipline. Test a new provider or settlement route in one corridor first. Confirm how funds are safeguarded, converted, withdrawn, recorded in accounting systems, and supported if a payment fails. Research into tokenized wholesale settlement is also progressing. The work toward real-value testing in Project Agorá illustrates how tokenized central bank reserves and commercial bank deposits are being explored for wholesale cross-border payments. For most businesses, however, current tools should be judged on proven controls, practical availability, and fit with existing workflows. A Practical Treasury Checklist 1. List every country and currency involved in sending or receiving funds. 2. Measure current fees, conversion spreads, and settlement times. 3. Set minimum cash reserves for essential obligations. 4. Create clear approval levels and maintain payment documentation. 5. Choose a primary and backup route for important payment corridors. 6. Connect payment records to accounting and reporting processes. 7. Test changes with smaller transactions before scaling them. 8. Review the full treasury process at least quarterly. Common Questions What Is A Cross-Border Treasury Plan? It is a written process for managing international cash, currencies, payment methods, reserves, approvals, and financial risk. Should A Small Business Have One? Yes. It can be as simple as a payment calendar, a cash spreadsheet, target currency balances, and clear approval rules. Are Faster Payments Always Better? No. Speed matters, but so do total cost, tracking, compliance checks, accuracy, and the ability to resolve exceptions. Conclusion A strong cross-border treasury plan combines clear records, sensible currency rules, reliable payment routes, and routine compliance checks. Businesses should test their processes, measure the actual cost of each corridor, maintain a backup option for urgent payments, and choose tools that improve both control and speed.
Finance

How Global Businesses Can Build A Smarter Cross-Border Treasury Plan

By Robert
9 hours ago
FAQs About Allergy Treatments
Health

FAQs About Allergy Treatments

By Robert
22 hours ago
The Future of Allergy Testing
Blog

The Future of Allergy Testing

By Robert
1 day ago
Using Therapy To Navigate the Challenges of Adult ADHD
Blog

Using Therapy To Navigate the Challenges of Adult ADHD

By Robert
4 days ago

Life Style

View All
How Does a Cosmetic Dentist Place Crowns and Veneers?
Health

How Does a Cosmetic Dentist Place Crowns and Veneers?

5 Min Read
How Global Businesses Can Build A Smarter Cross-Border Treasury Plan ________________________________________ Key Takeaways • A defined treasury plan helps reduce payment delays, avoidable conversion costs, and cash flow surprises. • Each payment corridor should be assessed for cost, speed, reliability, settlement timing, and compliance needs. • Currency balances, approval rules, and cash forecasts deserve the same attention as payment tools. • New settlement technology can be useful, but only with sound accounting, controls, and backup routes. International growth can create a cash management problem long before it creates a revenue problem. A company may collect payments in one currency, pay teams in several others, and still need dependable access to cash for taxes, suppliers, and payroll. An offshore business account may be part of that structure when it supports legitimate operational needs. Still, it should fit into a broader plan for visibility, approvals, recordkeeping, and currency management. A smarter treasury plan is not necessarily complicated. It is a practical system for knowing where money is held, what payments are due, how funds move between countries, and who can authorize each transaction. The goal is to make daily decisions more predictable while preserving flexibility when a supplier, customer, or market condition changes. Why Treasury Planning Matters For Global Businesses Cross-border payments involve more moving parts than domestic transfers. Currencies, banking hours, local payment systems, intermediary institutions, and legal frameworks can all affect the outcome. The complexity of payments across multiple jurisdictions helps explain why a transfer that seems routine can take longer or cost more than expected. Consider a software company that receives subscription revenue in euros, pays contractors in U.S. dollars, and settles local vendor invoices in other currencies. It can be profitable on paper while still facing a short-term cash constraint if customer receipts arrive late, conversion is delayed, or too much money is held in a currency that cannot cover the next obligation. Map Every Money Flow Start with a simple inventory of where money enters and leaves the business. Do not limit the review to major supplier payments. Small, recurring transactions and exception payments often reveal operational gaps. Include These Categories • Customer receipts, refunds, and chargebacks. • Supplier invoices, payroll, and contractor payments. • Taxes, government fees, and insurance obligations. • Transfers between company accounts and reserve balances. For each recurring flow, record the country, currency, usual amount, timing, recipient, payment method, and approver. Then ask where delays occur, which currencies create the greatest conversion expense, and how much cash must remain available over the next 30, 60, and 90 days. Choose The Right Payment Rails No single payment method works best for every corridor. Traditional bank transfers are well-suited to established supplier relationships and higher-value payments. Local payment networks may be practical for recurring in-country expenses. Card networks can support customer purchases and lower operating costs, while faster payment systems may improve access to funds where they are supported. Compare routes based on the total cost, quoted exchange rate, settlement time, delivery certainty, tracking, transaction limits, and refund process. A low upfront fee is not automatically the lowest-cost option if the exchange spread, manual work, or delayed settlement creates additional expense. Manage Currency Risk With Simple Rules Currency management should support operations rather than become speculation. Set target balances for the currencies used most often, keep enough local funds for near-term commitments, and convert excess balances according to a documented schedule. Forecast known needs before large invoices, payroll cycles, or tax deadlines. A practical policy might require the company to maintain a defined operating balance in each core currency, review material exposures monthly, and require additional approval for conversions above a chosen threshold. Track the full conversion cost, including fees and spreads, so decisions are based on actual results. Build Compliance Controls Into The Process Faster payments do not remove the need for verification. Confirm the legal name and account details for each recipient, retain invoices and contracts with payment records, and set approval limits that reflect the payment value and risk. Unusual, high-value, or first-time transfers should receive closer review. Requirements can differ by jurisdiction, industry, and transaction type. Businesses should review relevant sanctions, reporting, tax, and recordkeeping duties, then seek qualified legal or tax advice when a requirement is unclear. Improve Cash Visibility A basic dashboard can turn fragmented account data into useful decisions. Track available cash by currency, expected receipts, upcoming payments by country, reserve balances, delayed transfers, failed payments, average settlement time, and average conversion cost. Businesses with frequent international activity should review this information weekly. Companies with fewer transactions may use a monthly review, provided they also monitor upcoming deadlines and major currency exposures between reviews. Use New Payment Tools With Care Technology can improve automation, reconciliation, and speed, but it does not replace operational discipline. Test a new provider or settlement route in one corridor first. Confirm how funds are safeguarded, converted, withdrawn, recorded in accounting systems, and supported if a payment fails. Research into tokenized wholesale settlement is also progressing. The work toward real-value testing in Project Agorá illustrates how tokenized central bank reserves and commercial bank deposits are being explored for wholesale cross-border payments. For most businesses, however, current tools should be judged on proven controls, practical availability, and fit with existing workflows. A Practical Treasury Checklist 1. List every country and currency involved in sending or receiving funds. 2. Measure current fees, conversion spreads, and settlement times. 3. Set minimum cash reserves for essential obligations. 4. Create clear approval levels and maintain payment documentation. 5. Choose a primary and backup route for important payment corridors. 6. Connect payment records to accounting and reporting processes. 7. Test changes with smaller transactions before scaling them. 8. Review the full treasury process at least quarterly. Common Questions What Is A Cross-Border Treasury Plan? It is a written process for managing international cash, currencies, payment methods, reserves, approvals, and financial risk. Should A Small Business Have One? Yes. It can be as simple as a payment calendar, a cash spreadsheet, target currency balances, and clear approval rules. Are Faster Payments Always Better? No. Speed matters, but so do total cost, tracking, compliance checks, accuracy, and the ability to resolve exceptions. Conclusion A strong cross-border treasury plan combines clear records, sensible currency rules, reliable payment routes, and routine compliance checks. Businesses should test their processes, measure the actual cost of each corridor, maintain a backup option for urgent payments, and choose tools that improve both control and speed.
Finance

How Global Businesses Can Build A Smarter Cross-Border Treasury Plan

8 Min Read
FAQs About Allergy Treatments
Health

FAQs About Allergy Treatments

4 Min Read
The Future of Allergy Testing
Blog

The Future of Allergy Testing

5 Min Read
Using Therapy To Navigate the Challenges of Adult ADHD
Blog

Using Therapy To Navigate the Challenges of Adult ADHD

4 Min Read

Health

The Future of Allergy Testing
Blog

The Future of Allergy Testing

1 day ago
Using Therapy To Navigate the Challenges of Adult ADHD
Blog

Using Therapy To Navigate the Challenges of Adult ADHD

4 days ago
Blog

6 Brand Kit Partners That Make Custom Trucker Hats Work Harder

2 weeks ago
A Child-Centered Plan for High-Conflict Co-Parenting
Blog

A Child-Centered Plan for High-Conflict Co-Parenting

1 month ago
5 Best Recruiting CRM And ATS Platforms For Better Hiring Workflows
Blog

5 Best Recruiting CRM And ATS Platforms For Better Hiring Workflows

1 month ago
Blog

How to Use YMCAEUC.org for Community Services

1 month ago
Blog

Advanced Investment Strategies for Professionals

1 month ago
Blog

Top Business Strategies Every Entrepreneur Should Know

1 month ago

More News

View All
Alternative Therapies for Neck Pain Treatment
Health

Alternative Therapies for Neck Pain Treatment

4 hours ago
How Does a Cosmetic Dentist Place Crowns and Veneers?
Health

How Does a Cosmetic Dentist Place Crowns and Veneers?

4 hours ago
How Global Businesses Can Build A Smarter Cross-Border Treasury Plan ________________________________________ Key Takeaways • A defined treasury plan helps reduce payment delays, avoidable conversion costs, and cash flow surprises. • Each payment corridor should be assessed for cost, speed, reliability, settlement timing, and compliance needs. • Currency balances, approval rules, and cash forecasts deserve the same attention as payment tools. • New settlement technology can be useful, but only with sound accounting, controls, and backup routes. International growth can create a cash management problem long before it creates a revenue problem. A company may collect payments in one currency, pay teams in several others, and still need dependable access to cash for taxes, suppliers, and payroll. An offshore business account may be part of that structure when it supports legitimate operational needs. Still, it should fit into a broader plan for visibility, approvals, recordkeeping, and currency management. A smarter treasury plan is not necessarily complicated. It is a practical system for knowing where money is held, what payments are due, how funds move between countries, and who can authorize each transaction. The goal is to make daily decisions more predictable while preserving flexibility when a supplier, customer, or market condition changes. Why Treasury Planning Matters For Global Businesses Cross-border payments involve more moving parts than domestic transfers. Currencies, banking hours, local payment systems, intermediary institutions, and legal frameworks can all affect the outcome. The complexity of payments across multiple jurisdictions helps explain why a transfer that seems routine can take longer or cost more than expected. Consider a software company that receives subscription revenue in euros, pays contractors in U.S. dollars, and settles local vendor invoices in other currencies. It can be profitable on paper while still facing a short-term cash constraint if customer receipts arrive late, conversion is delayed, or too much money is held in a currency that cannot cover the next obligation. Map Every Money Flow Start with a simple inventory of where money enters and leaves the business. Do not limit the review to major supplier payments. Small, recurring transactions and exception payments often reveal operational gaps. Include These Categories • Customer receipts, refunds, and chargebacks. • Supplier invoices, payroll, and contractor payments. • Taxes, government fees, and insurance obligations. • Transfers between company accounts and reserve balances. For each recurring flow, record the country, currency, usual amount, timing, recipient, payment method, and approver. Then ask where delays occur, which currencies create the greatest conversion expense, and how much cash must remain available over the next 30, 60, and 90 days. Choose The Right Payment Rails No single payment method works best for every corridor. Traditional bank transfers are well-suited to established supplier relationships and higher-value payments. Local payment networks may be practical for recurring in-country expenses. Card networks can support customer purchases and lower operating costs, while faster payment systems may improve access to funds where they are supported. Compare routes based on the total cost, quoted exchange rate, settlement time, delivery certainty, tracking, transaction limits, and refund process. A low upfront fee is not automatically the lowest-cost option if the exchange spread, manual work, or delayed settlement creates additional expense. Manage Currency Risk With Simple Rules Currency management should support operations rather than become speculation. Set target balances for the currencies used most often, keep enough local funds for near-term commitments, and convert excess balances according to a documented schedule. Forecast known needs before large invoices, payroll cycles, or tax deadlines. A practical policy might require the company to maintain a defined operating balance in each core currency, review material exposures monthly, and require additional approval for conversions above a chosen threshold. Track the full conversion cost, including fees and spreads, so decisions are based on actual results. Build Compliance Controls Into The Process Faster payments do not remove the need for verification. Confirm the legal name and account details for each recipient, retain invoices and contracts with payment records, and set approval limits that reflect the payment value and risk. Unusual, high-value, or first-time transfers should receive closer review. Requirements can differ by jurisdiction, industry, and transaction type. Businesses should review relevant sanctions, reporting, tax, and recordkeeping duties, then seek qualified legal or tax advice when a requirement is unclear. Improve Cash Visibility A basic dashboard can turn fragmented account data into useful decisions. Track available cash by currency, expected receipts, upcoming payments by country, reserve balances, delayed transfers, failed payments, average settlement time, and average conversion cost. Businesses with frequent international activity should review this information weekly. Companies with fewer transactions may use a monthly review, provided they also monitor upcoming deadlines and major currency exposures between reviews. Use New Payment Tools With Care Technology can improve automation, reconciliation, and speed, but it does not replace operational discipline. Test a new provider or settlement route in one corridor first. Confirm how funds are safeguarded, converted, withdrawn, recorded in accounting systems, and supported if a payment fails. Research into tokenized wholesale settlement is also progressing. The work toward real-value testing in Project Agorá illustrates how tokenized central bank reserves and commercial bank deposits are being explored for wholesale cross-border payments. For most businesses, however, current tools should be judged on proven controls, practical availability, and fit with existing workflows. A Practical Treasury Checklist 1. List every country and currency involved in sending or receiving funds. 2. Measure current fees, conversion spreads, and settlement times. 3. Set minimum cash reserves for essential obligations. 4. Create clear approval levels and maintain payment documentation. 5. Choose a primary and backup route for important payment corridors. 6. Connect payment records to accounting and reporting processes. 7. Test changes with smaller transactions before scaling them. 8. Review the full treasury process at least quarterly. Common Questions What Is A Cross-Border Treasury Plan? It is a written process for managing international cash, currencies, payment methods, reserves, approvals, and financial risk. Should A Small Business Have One? Yes. It can be as simple as a payment calendar, a cash spreadsheet, target currency balances, and clear approval rules. Are Faster Payments Always Better? No. Speed matters, but so do total cost, tracking, compliance checks, accuracy, and the ability to resolve exceptions. Conclusion A strong cross-border treasury plan combines clear records, sensible currency rules, reliable payment routes, and routine compliance checks. Businesses should test their processes, measure the actual cost of each corridor, maintain a backup option for urgent payments, and choose tools that improve both control and speed.
Finance

How Global Businesses Can Build A Smarter Cross-Border Treasury Plan

9 hours ago
FAQs About Allergy Treatments
Health

FAQs About Allergy Treatments

22 hours ago
The Future of Allergy Testing
Blog

The Future of Allergy Testing

1 day ago
Using Therapy To Navigate the Challenges of Adult ADHD
Blog

Using Therapy To Navigate the Challenges of Adult ADHD

4 days ago
How to Make Preventive Dental Care Fit Your Budget
Health

How to Make Preventive Dental Care Fit Your Budget

5 days ago
The Role of Chiropractic Care in Treating Pediatric Conditions
Health

The Role of Chiropractic Care in Treating Pediatric Conditions

1 week ago
travel

Family-Friendly Beach Resorts for a Long Weekend

2 weeks ago
Finance

Is Your Employer’s Group Health Insurance Really Enough?

2 weeks ago
Business

Leveraging Data and AI for Effective Marketing Campaigns

2 weeks ago
Blog

6 Brand Kit Partners That Make Custom Trucker Hats Work Harder

2 weeks ago
How Does a Cosmetic Dentist Place Crowns and Veneers?
Health

How Does a Cosmetic Dentist Place Crowns and Veneers?

How Global Businesses Can Build A Smarter Cross-Border Treasury Plan ________________________________________ Key Takeaways • A defined treasury plan helps reduce payment delays, avoidable conversion costs, and cash flow surprises. • Each payment corridor should be assessed for cost, speed, reliability, settlement timing, and compliance needs. • Currency balances, approval rules, and cash forecasts deserve the same attention as payment tools. • New settlement technology can be useful, but only with sound accounting, controls, and backup routes. International growth can create a cash management problem long before it creates a revenue problem. A company may collect payments in one currency, pay teams in several others, and still need dependable access to cash for taxes, suppliers, and payroll. An offshore business account may be part of that structure when it supports legitimate operational needs. Still, it should fit into a broader plan for visibility, approvals, recordkeeping, and currency management. A smarter treasury plan is not necessarily complicated. It is a practical system for knowing where money is held, what payments are due, how funds move between countries, and who can authorize each transaction. The goal is to make daily decisions more predictable while preserving flexibility when a supplier, customer, or market condition changes. Why Treasury Planning Matters For Global Businesses Cross-border payments involve more moving parts than domestic transfers. Currencies, banking hours, local payment systems, intermediary institutions, and legal frameworks can all affect the outcome. The complexity of payments across multiple jurisdictions helps explain why a transfer that seems routine can take longer or cost more than expected. Consider a software company that receives subscription revenue in euros, pays contractors in U.S. dollars, and settles local vendor invoices in other currencies. It can be profitable on paper while still facing a short-term cash constraint if customer receipts arrive late, conversion is delayed, or too much money is held in a currency that cannot cover the next obligation. Map Every Money Flow Start with a simple inventory of where money enters and leaves the business. Do not limit the review to major supplier payments. Small, recurring transactions and exception payments often reveal operational gaps. Include These Categories • Customer receipts, refunds, and chargebacks. • Supplier invoices, payroll, and contractor payments. • Taxes, government fees, and insurance obligations. • Transfers between company accounts and reserve balances. For each recurring flow, record the country, currency, usual amount, timing, recipient, payment method, and approver. Then ask where delays occur, which currencies create the greatest conversion expense, and how much cash must remain available over the next 30, 60, and 90 days. Choose The Right Payment Rails No single payment method works best for every corridor. Traditional bank transfers are well-suited to established supplier relationships and higher-value payments. Local payment networks may be practical for recurring in-country expenses. Card networks can support customer purchases and lower operating costs, while faster payment systems may improve access to funds where they are supported. Compare routes based on the total cost, quoted exchange rate, settlement time, delivery certainty, tracking, transaction limits, and refund process. A low upfront fee is not automatically the lowest-cost option if the exchange spread, manual work, or delayed settlement creates additional expense. Manage Currency Risk With Simple Rules Currency management should support operations rather than become speculation. Set target balances for the currencies used most often, keep enough local funds for near-term commitments, and convert excess balances according to a documented schedule. Forecast known needs before large invoices, payroll cycles, or tax deadlines. A practical policy might require the company to maintain a defined operating balance in each core currency, review material exposures monthly, and require additional approval for conversions above a chosen threshold. Track the full conversion cost, including fees and spreads, so decisions are based on actual results. Build Compliance Controls Into The Process Faster payments do not remove the need for verification. Confirm the legal name and account details for each recipient, retain invoices and contracts with payment records, and set approval limits that reflect the payment value and risk. Unusual, high-value, or first-time transfers should receive closer review. Requirements can differ by jurisdiction, industry, and transaction type. Businesses should review relevant sanctions, reporting, tax, and recordkeeping duties, then seek qualified legal or tax advice when a requirement is unclear. Improve Cash Visibility A basic dashboard can turn fragmented account data into useful decisions. Track available cash by currency, expected receipts, upcoming payments by country, reserve balances, delayed transfers, failed payments, average settlement time, and average conversion cost. Businesses with frequent international activity should review this information weekly. Companies with fewer transactions may use a monthly review, provided they also monitor upcoming deadlines and major currency exposures between reviews. Use New Payment Tools With Care Technology can improve automation, reconciliation, and speed, but it does not replace operational discipline. Test a new provider or settlement route in one corridor first. Confirm how funds are safeguarded, converted, withdrawn, recorded in accounting systems, and supported if a payment fails. Research into tokenized wholesale settlement is also progressing. The work toward real-value testing in Project Agorá illustrates how tokenized central bank reserves and commercial bank deposits are being explored for wholesale cross-border payments. For most businesses, however, current tools should be judged on proven controls, practical availability, and fit with existing workflows. A Practical Treasury Checklist 1. List every country and currency involved in sending or receiving funds. 2. Measure current fees, conversion spreads, and settlement times. 3. Set minimum cash reserves for essential obligations. 4. Create clear approval levels and maintain payment documentation. 5. Choose a primary and backup route for important payment corridors. 6. Connect payment records to accounting and reporting processes. 7. Test changes with smaller transactions before scaling them. 8. Review the full treasury process at least quarterly. Common Questions What Is A Cross-Border Treasury Plan? It is a written process for managing international cash, currencies, payment methods, reserves, approvals, and financial risk. Should A Small Business Have One? Yes. It can be as simple as a payment calendar, a cash spreadsheet, target currency balances, and clear approval rules. Are Faster Payments Always Better? No. Speed matters, but so do total cost, tracking, compliance checks, accuracy, and the ability to resolve exceptions. Conclusion A strong cross-border treasury plan combines clear records, sensible currency rules, reliable payment routes, and routine compliance checks. Businesses should test their processes, measure the actual cost of each corridor, maintain a backup option for urgent payments, and choose tools that improve both control and speed.
Finance

How Global Businesses Can Build A Smarter Cross-Border Treasury Plan

FAQs About Allergy Treatments
Health

FAQs About Allergy Treatments

The Future of Allergy Testing
Blog

The Future of Allergy Testing

Using Therapy To Navigate the Challenges of Adult ADHD
Blog

Using Therapy To Navigate the Challenges of Adult ADHD

How to Make Preventive Dental Care Fit Your Budget
Health

How to Make Preventive Dental Care Fit Your Budget

The Role of Chiropractic Care in Treating Pediatric Conditions
Health

The Role of Chiropractic Care in Treating Pediatric Conditions

travel

Family-Friendly Beach Resorts for a Long Weekend

Finance

Is Your Employer’s Group Health Insurance Really Enough?

Business

Leveraging Data and AI for Effective Marketing Campaigns

Blog

6 Brand Kit Partners That Make Custom Trucker Hats Work Harder

Reaper Scans

We are dedicated to helping businesses grow with innovative ideas, professional solutions, and reliable digital services. Our goal is to deliver quality, creativity, and success through modern business strategies tailored to every client’s needs.

Follow US

@ 2026 Reaperscanss.com. Powered by WordPress.

All the latest Reaperscanss.com news straight to your inbox​

Subscribe to our newsletter to get our newest articles instantly!
  • Business
  • Lifestyle
  • Health
  • Travel
  • Crypto
  • Finance
  • Blog
Welcome Back!

Sign in to your account

Username or Email Address
Password

Lost your password?